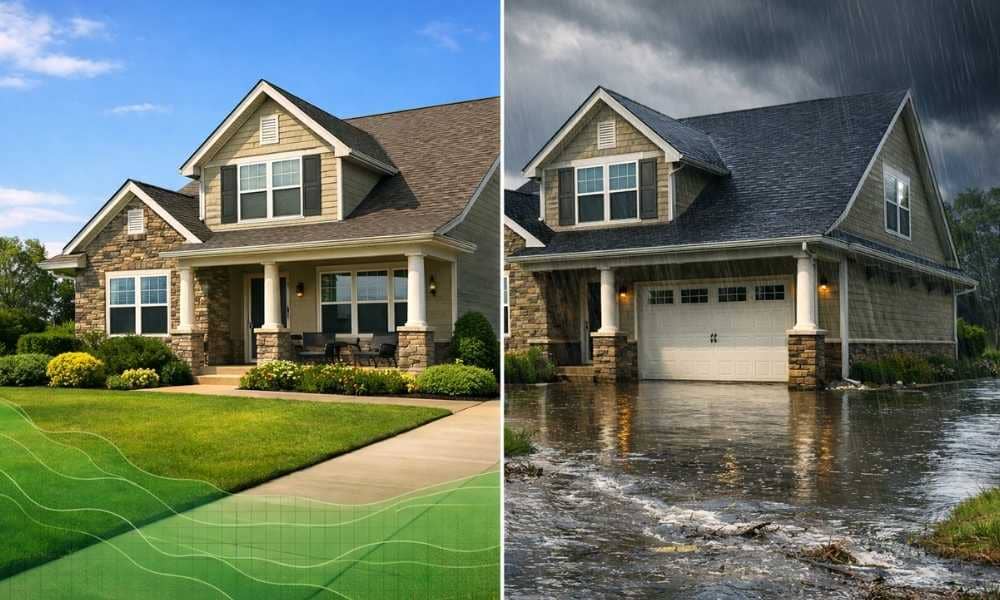
Your home sits safely outside the FEMA flood zone. You checked the federal maps, and your neighborhood shows green. No flood insurance required. You’re good, right?
Not necessarily.
A land survey matters when FEMA maps miss flood risk, and it happens more often than most homeowners realize. Recent reports show that nearly half of the homes that flooded in Orange County during 2024 and 2025 were located in areas that FEMA classified as safe. The problem is not with FEMA itself. Federal flood maps rely on data that is 5 to 10 years old. They use broad regional models that don’t capture the specific conditions of your property. Meanwhile, Florida is sinking, neighborhoods are changing, and storms are getting stronger.
This is where a professional land survey comes in.
How FEMA Maps Work (And Where They Fall Short)
FEMA creates flood maps based on historical flood records, river models, and storm surge predictions. These maps identify zones where flooding has a 1 percent chance of happening each year. This is what people call the “100-year flood.”
The process sounds solid. But it has real limitations.
FEMA maps don’t account for subsidence, the slow sinking of land over time. Central Florida has experienced 0.5 to 2 inches of subsidence per decade since the 1960s because of groundwater pumping. That means your property may have dropped significantly since FEMA’s last update. A home that sat above the flood line in 2015 might sit below it today.
Poor drainage systems also escape FEMA’s attention. Orange County’s stormwater systems were built in the 1960s for a much smaller population. Today, with over 1.3 million people, those systems are undersized. They cannot handle the rainfall that falls during major storms. Heavy rain pools in yards and streets, flooding homes that the map says are safe.
Development changes the picture too. When new neighborhoods are built upstream, they create more impervious surfaces like roofs and pavement. This increases runoff and directs water toward older areas downhill. FEMA maps cannot update fast enough to reflect these changes.
What a Professional Survey Reveals
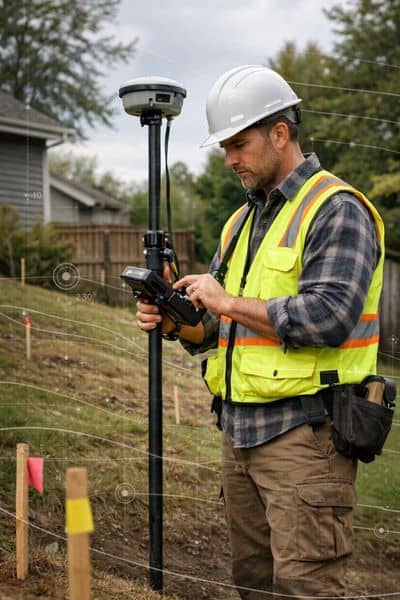
A land surveyor does something FEMA cannot do. They measure your specific property with precision that is accurate to within 0.01 feet. This is one hundred times more accurate than federal flood models.
Surveyors determine your home’s elevation and compare it to the Base Flood Elevation, or BFE. This is the height that floodwater is predicted to reach in your flood zone. If your foundation sits below the BFE, you face genuine flood risk. If you sit above it, you may qualify for lower insurance rates.
Beyond elevation numbers, surveyors map your property’s drainage patterns. They identify how water flows across your yard and neighboring properties. They locate retention ponds, ditches, swales, and other features that affect water movement. They note areas where water naturally pools during heavy rain. This microhydrology, the small-scale water movement specific to your location, cannot be seen on any FEMA map.
A surveyor can also document property features that increase flood risk. These include proximity to lakes and creeks, the direction that neighboring properties slope toward yours, and the presence of basements. This information shapes your actual risk profile.
The Orlando Reality
News 6 conducted an investigation in 2025 and found something troubling. Forty-seven percent of flood claims in Orange County came from properties outside FEMA high-risk zones. These were homes in X and C zones, areas the federal government classified as having minimal or moderate risk.
The reasons varied by neighborhood. In some areas, aging stormwater pipes had collapsed. In others, retention ponds overflowed because they were designed for rainfall patterns from decades past. Climate change has intensified storms beyond what old systems can handle. Subsidence had pushed properties closer to dangerous water levels.
Homeowners in these neighborhoods reported the same frustration. Their real estate agents had said the homes were safe. FEMA maps showed low risk. Yet water still entered their basements and yards when heavy rain fell.
This gap between the map and reality created financial losses. The average flood claim in Orange County exceeded $32,500. Most homeowners had no flood insurance because FEMA had not required it. They had to pay for repairs themselves.
How a Survey Protects Your Investment
Getting a professional survey before buying a home is one of the smartest financial decisions you can make. The cost is between $500 and $1,000. The information you receive can save you tens of thousands of dollars.
A surveyor provides an Elevation Certificate, a document that shows your home’s exact elevation compared to the Base Flood Elevation. If this certificate proves your foundation sits above the BFE, your flood insurance premium may drop by $300 to $1,200 per year. Over a decade, that amounts to $3,000 to $12,000 in savings. For more information on how flood insurance premiums are calculated, visit FloodSmart.gov.
The certificate also supports a formal request to FEMA called a Letter of Map Amendment, or LOMA. This document asks FEMA to remove your property from the floodplain based on new survey data. In Florida, about 35 to 45 percent of LOMA requests succeed. If yours does, you may no longer need flood insurance at all. The annual savings could exceed $1,500.
Beyond insurance, a survey informs your decisions about mitigation. If water naturally drains toward your home, you might invest in grading improvements or French drains. If your foundation sits below the BFE, you might consider elevation work. Surveys tell you exactly what mitigation makes sense for your property and what the return on investment will be.
When Should You Get a Flood Survey?
You should invest in a professional survey if you are buying a home outside FEMA flood zones. The false confidence that FEMA creates is dangerous. You should also get a survey if your property sits within 500 feet of a lake, pond, or creek. Water levels rise and fall. Surveys measure your actual elevation and distance to these features.
Older neighborhoods with aging stormwater systems also warrant a survey. Properties on flat terrain with poor natural drainage benefit from professional assessment. If you are planning construction, an addition, or an accessory dwelling unit, a survey provides the baseline elevation you need for planning and permitting.
Even if you already own your home, a survey makes sense if you are refinancing after FEMA map updates or if you want to establish a baseline for detecting subsidence over time.
The Takeaway
FEMA maps serve an important purpose, but they are not designed to assess risk for individual properties. They reflect old data, broad regional patterns, and historical conditions that may no longer apply to your specific location. A professional land survey fills this gap. It reveals the true flood risk on your property and provides the data you need to make informed decisions about insurance, mitigation, and home purchases.
If you would like to discuss your property’s flood risk or want to understand your options, reach out to discuss your situation with a licensed surveyor who can provide specific guidance for your home.